Before a lender agrees to a short sale, prepares a foreclosure bid, or decides how to recover a delinquent mortgage, someone must estimate the property's value. That estimate can influence the financial outcome for both the lender and the homeowner.
A homeowner purchases a property for $350,000. Years later, the surrounding neighborhood has appreciated, and similar homes are selling for $500,000.
But after a financial hardship causes the homeowner to fall behind on mortgage payments, the property enters the mortgage default system.
The mortgage servicer orders a valuation. The resulting estimate places the home's value at $425,000.
That $75,000 difference between the estimate and nearby selling prices could become important in negotiations over a short sale, decisions about foreclosure bidding, or the homeowner's assessment of how much equity remains.
The example is hypothetical, but the underlying issue is real: the value assigned to a distressed property can influence decisions involving hundreds of thousands of dollars.
Yet many homeowners know little about how mortgage companies obtain those valuations, who performs them, or whether the estimates accurately reflect the property's condition and local real estate market.
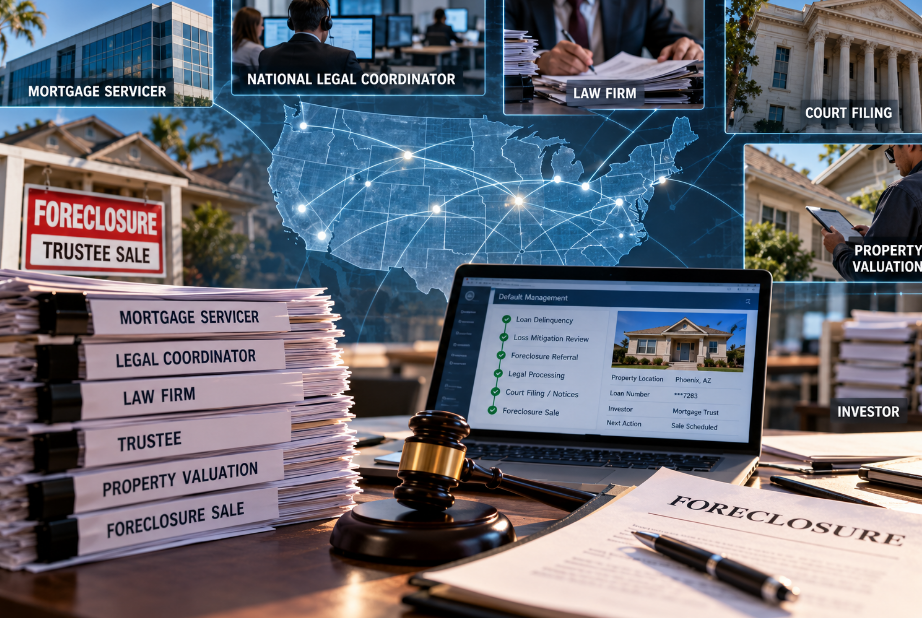
Property valuation is a specialized component of the mortgage default industry. It connects real estate professionals, financial institutions, mortgage servicers, valuation technology companies, and foreclosure operations.
Understanding how it works is essential to understanding what happens financially when a home approaches foreclosure.
Why Mortgage Companies Value Properties in Default
When a borrower stops making mortgage payments, the property securing the loan becomes central to the creditor's recovery analysis.
A mortgage investor may need to determine whether the property is worth more or less than the outstanding debt.
The answer can influence decisions about loan modifications, short sales, deeds in lieu of foreclosure, foreclosure bidding, and the eventual disposition of a property acquired through foreclosure.
Consider a home securing a $300,000 mortgage.
If the property's estimated market value is $450,000, the homeowner may possess substantial equity before accounting for other liens and selling expenses.
If the same property is worth only $250,000, the loan may be underwater, meaning the mortgage balance exceeds the estimated property value.
Those situations present different financial considerations.
A homeowner with substantial equity may be able to sell the property, satisfy the mortgage, and retain remaining proceeds.
An underwater homeowner may require the lender's approval to complete a short sale for less than the outstanding balance.
For the mortgage investor, the expected recovery from a foreclosure depends not only on the property's estimated value but also on foreclosure costs, taxes, other liens, property condition, and the time required to sell.
That makes valuation an important financial decision-making tool.
The Different Ways a Home Is Valued
Mortgage companies do not always use traditional residential appraisals when evaluating distressed properties.
Depending on the purpose, applicable law, investor requirements, and circumstances, several valuation methods may be available.
Traditional Real Estate Appraisals
A real estate appraisal is a professional opinion of property value developed using recognized appraisal methods.
An appraiser may analyze comparable property sales, the home's physical characteristics, neighborhood conditions, and other relevant market information.
The appraisal may involve an interior inspection, an exterior inspection, or another permitted approach, depending on the assignment and applicable requirements.
Appraisals can provide detailed support for a value conclusion, but they require professional judgment and appropriate data.
Two competent appraisers can sometimes reach different conclusions, particularly when comparable sales are limited or the property has unusual characteristics.
An appraisal is therefore an informed estimate of value, not a guarantee of what a property will sell for.
Broker Price Opinions
A broker price opinion, commonly called a BPO, is an estimate of a property's probable selling price prepared by a real estate broker or salesperson.
BPOs are commonly used in mortgage servicing and loss mitigation.
They may rely on comparable sales, current listings, property condition, and local market knowledge.
Some involve interior inspections, while others are conducted using exterior observations and available records.
BPOs can be less expensive and faster to obtain than full appraisals.
However, a BPO is not necessarily equivalent to an appraisal, and state laws may restrict when a broker price opinion can be used or how it may be represented.
The distinction matters when a valuation becomes the basis for an important financial decision.
Automated Valuation Models
Automated valuation models, or AVMs, use computer-based methods to estimate real estate values.
These systems may analyze property records, recent sales, geographic information, market trends, and other datasets.
Their principal advantages include speed, scalability, and the ability to estimate values across large portfolios.
A mortgage company managing thousands of loans can use automated systems to obtain estimates far more quickly than commissioning individual property inspections for every loan.
But automated models have limitations.
They may not fully account for recent renovations, structural damage, unusual property features, or neighborhood changes that are not adequately reflected in the underlying data.
An AVM estimate can also be affected by incomplete or inaccurate property records.
These limitations become particularly important when a model's estimate differs substantially from actual local market conditions.
The Rise of Automated Property Valuations
Technology has changed how financial institutions evaluate real estate collateral.
Instead of relying exclusively on individual appraisers, mortgage companies can incorporate automated valuations into large-scale servicing operations.
Fannie Mae, for example, maintains servicing systems that allow authorized users to retrieve automated valuation estimates and confidence scores for certain loss mitigation activities.
Its systems also support valuation orders associated with short sales, deeds in lieu of foreclosure, and foreclosure bidding decisions.
This demonstrates how property valuation has become integrated into broader mortgage default operations.
A valuation may be requested, received, and incorporated into a servicing decision through an electronic workflow.
The benefits can be substantial.
Automated systems can reduce processing time, lower certain administrative costs, and provide standardized information across large loan portfolios.
But the use of technology also raises questions about reliability.
A model may produce a precise dollar amount even when its underlying estimate contains considerable uncertainty.
The existence of a numerical result does not eliminate the need to consider whether the information supporting it is appropriate for the particular property.
Federal Regulators Have Established Standards for Certain Automated Valuations
Concerns about automated valuation accuracy have received attention from federal financial regulators.
In 2024, six federal agencies adopted a final rule establishing quality-control standards for automated valuation models used in specified mortgage-related transactions.
The rule became effective October 1, 2025.
For covered mortgage originators and secondary market issuers, the regulation requires policies and controls designed to support confidence in valuation estimates, protect against data manipulation, address conflicts of interest, require sample testing and reviews, and comply with applicable nondiscrimination laws.
The rule reflects a recognition that automated valuation technology can affect important financial decisions.
However, its scope is limited.
It applies to specified credit decisions and securitization determinations involving mortgages secured by a consumer's principal dwelling. It should not be interpreted as imposing identical requirements on every valuation used in foreclosure servicing.
Different valuation activities remain subject to different legal, contractual, and professional requirements.
Nevertheless, the federal standards illustrate a broader concern: property valuation systems must be evaluated for accuracy, integrity, and appropriate use.
How Valuations Influence Short Sales
Property valuation becomes especially important when a homeowner seeks permission to sell a property for less than the mortgage balance.
In a short sale, the mortgage holder generally must agree to accept the transaction under applicable terms because the sale proceeds will not fully satisfy the secured debt.
The lender or investor therefore needs to determine whether the proposed sale price is reasonable.
An estimate that is too high may cause the mortgage company to reject an otherwise realistic offer.
An estimate that is too low may lead to a transaction that fails to capture the property's potential market value.
Fannie Mae's servicing requirements illustrate the importance of this process.
For qualifying short-sale evaluations, its guide requires the servicer to obtain a property valuation through Fannie Mae's designated process.
The valuation must be sufficiently current, and the servicer must follow specific requirements when evaluating the proposed transaction.
The guide also recognizes that suggested listing prices are guidance rather than guarantees that a particular offer will be approved.
For homeowners, this means the lender's assessment of value can become a central factor in whether a short sale succeeds.
A disagreement about value may complicate negotiations even when both the borrower and a prospective buyer are prepared to complete the transaction.
What Happens When a Property Is Undervalued?
An inaccurate valuation does not necessarily cause a foreclosure or establish that a mortgage company has acted unlawfully.
But a material error can affect financial decisions.
Suppose a home has an actual market value of approximately $500,000, but a servicing valuation estimates it at $400,000.
That difference may influence the servicer's recovery projections or the homeowner's understanding of available options.
The consequences depend on how the valuation is used.
A low estimate could influence a proposed short-sale price or a creditor's internal bidding strategy.
A high estimate could make a realistic short-sale offer appear inadequate.
In either case, the concern is whether the estimate reasonably reflects the property's market conditions and physical characteristics.
It is also important to distinguish a property's estimated market value from the price obtained at a foreclosure auction.
Foreclosure auctions may attract a narrower group of buyers, involve limited inspection opportunities, require rapid payment, or present uncertainties concerning possession and property condition.
As a result, a foreclosure sale price may differ substantially from an estimated market value.
That difference, by itself, does not prove that the property was improperly valued.
The Relationship Between Home Value and Homeowner Equity
One of the most important concepts in foreclosure is homeowner equity.
Equity generally represents the difference between the property's value and the debt and other obligations secured against it.
For example, a property worth $500,000 with a $300,000 mortgage has approximately $200,000 in gross equity before considering other liens and transaction expenses.
That equity may represent years of mortgage payments, appreciation, and financial investment.
When foreclosure occurs, the distribution of sale proceeds is governed by applicable state law and lien priorities.
Foreclosure expenses and secured obligations may be paid from the proceeds, and any legally required surplus may be distributed to junior lienholders or the former owner, depending on the circumstances.
But homeowners should not assume that a property with substantial market value will necessarily produce a substantial surplus at auction.
The actual sale price, outstanding debt, lien priorities, costs, and state procedures all matter.
Likewise, a lender's internal valuation does not by itself determine how much money the homeowner will receive.
The financial outcome depends on the legal and economic circumstances of the transaction.
Who Is Responsible for an Inaccurate Valuation?
Responsibility for a valuation problem depends on the nature of the error, the parties involved, and the purpose for which the valuation was prepared.
A licensed appraiser may be subject to professional standards and applicable state licensing requirements.
A real estate broker preparing a BPO may have obligations under state law and the terms of the assignment.
A mortgage servicer may be responsible for complying with applicable investor guidelines, contractual requirements, and laws governing its use of valuation information.
A financial institution using automated models in covered transactions may also be subject to federal quality-control requirements.
But not every inaccurate estimate creates a legal claim.
Establishing liability generally requires identifying an applicable legal duty, showing how it was violated, and satisfying any additional requirements for the particular cause of action.
An ordinary disagreement over market value is not automatically evidence of fraud, negligence, or misconduct.
The more meaningful questions concern whether the valuation method was appropriate, whether the information was reliable, and whether the responsible parties complied with the requirements governing the transaction.
Can a Homeowner Challenge a Property Valuation?
Homeowners who believe a valuation is inaccurate may have practical options for raising concerns, although there is no universal right to appeal every valuation used in default servicing.
A borrower may obtain an independent appraisal, review comparable property sales, document renovations or property conditions, or provide evidence of inaccuracies in public records.
During a short-sale review, the homeowner or real estate agent may be able to submit information supporting a different market value.
The availability of a formal reconsideration process depends on the particular loan program, investor requirements, valuation type, and applicable law.
A homeowner should also distinguish between challenging a valuation and stopping a foreclosure.
Providing evidence that a home is worth more than the lender estimated does not automatically suspend foreclosure proceedings.
Any applicable foreclosure deadline or legal requirement must be addressed separately.
This distinction is especially important when a property is already scheduled for sale.
The Financial Decisions Behind a Foreclosure
Property valuation may appear to be a technical exercise involving comparable sales, inspection reports, and mathematical models.
In reality, it can influence decisions with substantial consequences.
A valuation may help determine whether a short sale is approved, whether a mortgage investor expects to recover its debt, how a foreclosure bid is calculated, or how a property is managed after foreclosure.
For homeowners, the stakes include accumulated equity, potential sale proceeds, and the ability to evaluate alternatives before losing ownership.
For lenders and investors, valuations provide information needed to manage financial risk and recover secured debt.
These interests are not necessarily incompatible.
Both borrowers and creditors benefit from reliable information about the property securing the loan.
The problem arises when important decisions depend on estimates that have not been adequately verified or that fail to account for material facts.
A home's value should not be treated as merely another number in a mortgage servicing system. Behind that number may be a family's accumulated wealth, a creditor's recovery decision, and the financial consequences of a foreclosure that cannot easily be reversed.
As property valuation becomes increasingly automated, the central question is whether the systems producing those estimates remain sufficiently accurate, transparent, and accountable for the decisions they help shape.