Behind a foreclosure notice may be a network of mortgage servicers, national legal coordinators, local attorneys, trustees, and technology providers. Although foreclosure laws differ from state to state, much of the work involved in enforcing delinquent mortgages can be organized through centralized operations.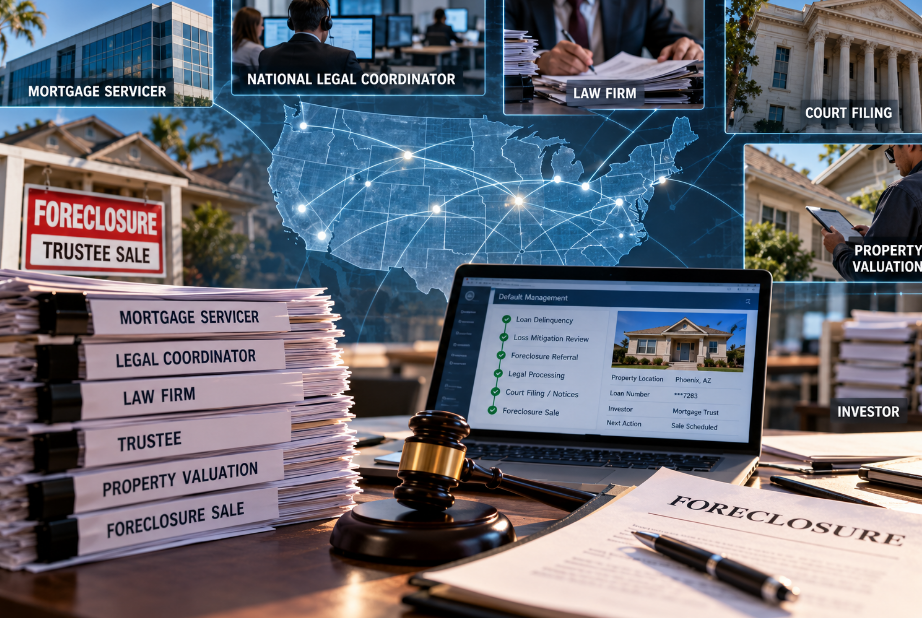
A homeowner in California receives a notice of default. A borrower in Florida is served with a foreclosure lawsuit. In Texas, a trustee prepares for a scheduled property auction. In New York, attorneys file documents in a judicial foreclosure proceeding.
The properties are located thousands of miles apart, and the legal procedures governing them are substantially different.
Yet the mortgage loans involved could be administered by the same national servicing company, with foreclosure-related work coordinated through a centralized network of attorneys, trustees, vendors, and technology systems.
This is the business of nationwide mortgage default legal services.
For financial institutions managing large portfolios of delinquent mortgages, foreclosure is not simply an isolated legal proceeding involving one borrower and one property.
It is an operational process requiring compliance with federal regulations, state foreclosure statutes, investor requirements, court procedures, and contractual obligations.
The companies responsible for coordinating that work form a specialized industry operating largely outside public view.
Understanding how the industry functions reveals an important reality: the entity communicating with a homeowner may be only one participant in a much larger network of organizations involved in the foreclosure process.
Why Nationwide Foreclosure Networks Exist
Mortgage lending has become a national financial business.
Banks, mortgage investors, government-sponsored enterprises, and other institutions may hold interests in loans secured by properties throughout the United States.
A mortgage servicer can administer loans in numerous jurisdictions, collecting payments, maintaining account records, handling borrower communications, and managing defaults.
When a borrower becomes seriously delinquent, the servicer may need to coordinate foreclosure-related activity in the state where the property is located.
That presents a substantial legal challenge.
Foreclosure law is not uniform throughout the country.
Some states primarily use judicial foreclosure, requiring a lawsuit and court involvement before a property can be sold.
Other states permit nonjudicial foreclosure through procedures involving trustees, recorded notices, statutory waiting periods, and public auctions.
Even among states using similar procedures, the requirements can differ.
Notice periods, borrower protections, sale procedures, redemption rights, deficiency judgments, and lien priorities are governed by jurisdiction-specific rules.
A national mortgage servicer therefore cannot assume that the same foreclosure documents and procedures will be legally sufficient everywhere.
To address these differences, servicers may retain networks of local attorneys, trustees, and specialized default-service providers.
Centralized operations can coordinate assignments, documentation, deadlines, reporting, and communications while local professionals perform functions requiring jurisdiction-specific authority.
The resulting structure combines national administration with state-level legal execution.
The Mortgage Servicer: The Center of the Operation
For many homeowners, the mortgage servicer is the most visible participant in the default process.
The servicer typically collects payments, maintains loan records, communicates with borrowers, and administers available loss mitigation options.
It may also be responsible for referring delinquent loans to foreclosure counsel when the applicable conditions have been satisfied.
But the servicer does not necessarily own the loan.
The mortgage may be held by an investor, trust, financial institution, or another entity entitled to enforce the obligation under applicable law.
Servicing arrangements can establish how the servicer must handle defaults, obtain approvals, communicate with legal counsel, and report developments.
This separation between loan ownership and loan administration can be confusing for borrowers.
A homeowner may make payments to one company while the mortgage is owned by another.
Foreclosure notices may then identify additional entities, including a trustee, mortgage assignee, foreclosure law firm, or authorized representative.
Each may have a different legal role.
Understanding those roles is essential when determining who has authority to enforce the mortgage and who is responsible for particular servicing decisions.
The Role of National Default Legal Coordinators
Some companies specialize in coordinating foreclosure-related legal services across multiple jurisdictions.
Rather than performing every legal task directly, these organizations may work with local counsel, trustees, and other service providers.
Their functions can include managing referrals, maintaining case information, tracking deadlines, coordinating documents, monitoring compliance, and reporting progress to mortgage servicers or investors.
A national coordinator may help organize work involving hundreds or thousands of properties located in different states.
For example, a centralized system might track when a foreclosure referral was issued, whether required documents have been received, which local firm is handling the matter, and whether a scheduled sale has been postponed.
Such coordination can reduce administrative duplication and provide consistent reporting.
But centralized coordination does not eliminate the need for properly authorized legal professionals.
Legal representation, court appearances, professional supervision, and other activities constituting the practice of law must comply with the requirements of the relevant jurisdiction.
A business arrangement that works in one state may require a different structure in another.
That distinction is particularly important when nationwide providers describe their ability to offer services across all 50 states.
Such coverage may depend on networks of separately licensed attorneys and other authorized professionals rather than a single firm independently practicing law in every jurisdiction.
Local Attorneys and Trustees Still Matter
Although a foreclosure may be managed through a national servicing platform, the actual enforcement process is governed by applicable state law.
In judicial foreclosure states, local attorneys may prepare complaints, serve pleadings, respond to defenses, seek judgments, and coordinate court-supervised sales.
In nonjudicial foreclosure states, trustees or other authorized parties may record notices, provide required communications, and conduct foreclosure auctions.
Some states impose specific qualifications or restrictions on who may act as a trustee.
Others establish particular rules governing attorney participation, foreclosure documentation, and sale procedures.
These requirements cannot simply be replaced by national operating policies.
For example, the legal process for foreclosing on a residential property in New York differs significantly from the nonjudicial procedures commonly used in California.
A national company may coordinate both matters, but the actual legal work must reflect those differences.
This makes local knowledge and compliance especially important.
A procedural error that appears minor from a centralized administrative perspective may have substantial consequences under the law of the state where the property is located.
How a Foreclosure Referral Moves Through the System
Consider a hypothetical mortgage that becomes seriously delinquent.
The servicer first maintains the account history and evaluates whether applicable foreclosure prerequisites have been satisfied.
For many covered residential mortgage loans, federal servicing regulations generally prohibit the first foreclosure notice or filing until the borrower is more than 120 days delinquent, subject to specified exceptions.
The servicer must also consider applicable loss mitigation restrictions, bankruptcy proceedings, court orders, and other circumstances affecting its ability to proceed.
Once a foreclosure referral is legally appropriate, the servicer may assign the matter to an attorney or trustee through its default-management system.
The referral can include loan information, relevant documents, property details, and instructions concerning the authorized scope of work.
The receiving firm or trustee then evaluates the matter under applicable state law.
Additional documentation may be required to establish the authority to enforce the mortgage, identify the proper parties, calculate amounts owed, or comply with notice requirements.
As the case progresses, information may move between the local provider and the servicer.
A centralized system may record significant events, such as the filing of a complaint, recording of a notice of default, scheduling of a sale, or entry of a court order.
If the borrower enters an approved loss mitigation arrangement or a court issues a stay, that information must be communicated to the parties responsible for foreclosure activity.
The effectiveness of the process depends on accurate information moving between the organizations involved.
Technology and the Industrialization of Foreclosure
Modern mortgage default operations depend heavily on technology.
Loan servicing platforms maintain payment histories and account information.
Default-management systems track legal referrals, deadlines, and case developments.
Document systems organize notices, assignments, affidavits, and other records.
Electronic communications connect mortgage servicers with law firms, trustees, and outside vendors.
These technologies can improve consistency, reduce administrative costs, and help organizations manage large numbers of cases.
But they also introduce risks.
An incorrect account balance may be transmitted from the servicing system to a legal provider.
A foreclosure hold may not be reflected promptly in the case-management platform.
A document may contain outdated information about the borrower, creditor, or property.
A standardized workflow may fail to recognize a circumstance requiring individualized legal review.
Not every technical error results in an unlawful foreclosure.
Nevertheless, the reliability of these systems matters because the information they produce may be used in legally significant actions.
A foreclosure notice generated through an automated workflow is still a legal document that must satisfy the applicable requirements.
Technology can assist compliance, but it cannot replace the legal responsibility of the people and organizations using it.
The Lessons of the Robo-Signing Controversy
The risks associated with high-volume foreclosure processing became especially visible during the mortgage foreclosure crisis that followed the collapse of the housing market in 2007 and 2008.
Investigations revealed serious concerns involving mortgage servicing practices, foreclosure documentation, and the execution of affidavits and other legal records.
The term robo-signing became associated with practices in which individuals signed large numbers of foreclosure-related documents without adequately verifying their contents or following required procedures.
The controversy raised questions about the accuracy of sworn statements, the reliability of mortgage records, and the oversight of foreclosure service providers.
In 2012, federal and state authorities announced a major mortgage servicing settlement involving five large financial institutions.
The National Mortgage Settlement addressed alleged servicing and foreclosure abuses and imposed servicing standards and other obligations.
The settlement demonstrated that problems within foreclosure operations could extend beyond individual cases and involve systemic weaknesses in large institutions.
It also illustrated the importance of oversight when mortgage enforcement activities are divided among multiple departments and outside providers.
The historical misconduct identified during that period should not be attributed to today's individual firms without specific supporting evidence.
But the broader lesson remains relevant: high-volume foreclosure systems require meaningful verification, supervision, and accountability.
Who Is Responsible When Something Goes Wrong?
One of the most important questions in nationwide foreclosure operations concerns responsibility.
Suppose a homeowner submits a complete loss mitigation application that triggers federal restrictions on foreclosure activity.
The servicing department receives the application, but a foreclosure sale remains scheduled through an outside trustee.
If the sale proceeds in violation of an applicable restriction, which organization is responsible?
The answer depends on the governing law, contractual relationships, specific conduct, and circumstances of the case.
Under federal mortgage-servicing regulations, a covered servicer must comply with applicable loss mitigation requirements.
The servicer's use of outside foreclosure counsel does not eliminate its regulatory responsibilities.
Attorneys and trustees may also have independent duties under state law, court rules, professional standards, and applicable contractual arrangements.
Responsibility is therefore not necessarily confined to the party whose name appears on the foreclosure notice.
But neither is every participant automatically liable for every error.
Legal accountability requires examining what each entity was obligated to do, what information it possessed, what actions it took, and whether those actions violated an applicable duty.
This is one reason the structure of a nationwide foreclosure network matters.
The Importance of Accurate Mortgage Records
A foreclosure depends on reliable information about the underlying loan.
The amount owed must be calculated under the applicable loan terms and law.
Payments, fees, advances, and other account activity must be properly recorded.
The party seeking enforcement must possess the authority required by the governing legal framework.
Documents supporting the foreclosure must satisfy applicable evidentiary, recording, and procedural requirements.
Problems in these areas can generate disputes over whether foreclosure is legally authorized.
For example, a borrower may challenge an incorrect payment history or contest whether the foreclosing party has established its right to enforce the obligation.
The legal significance of such disputes varies by jurisdiction.
An assignment irregularity does not automatically invalidate a foreclosure, and the applicable requirements for standing or authority differ among states.
Nevertheless, accurate records are foundational to lawful enforcement.
A nationwide operation managing large volumes of loans must maintain systems capable of identifying and correcting material errors before they affect legal proceedings.
The Role of Mortgage Investors
Mortgage investors may have substantial influence over how delinquent loans are administered.
Investors can establish servicing requirements concerning loss mitigation, foreclosure referrals, property valuations, bidding practices, and reporting.
Government-sponsored enterprises such as Fannie Mae and Freddie Mac publish servicing guidance for loans subject to their requirements.
Other mortgage investors may operate under different contractual frameworks.
Servicers must consider these investor requirements alongside federal regulations and state law.
This can create a complicated decision-making structure.
A homeowner may negotiate with the servicer, while the available modification options are influenced by the requirements of the mortgage owner or investor.
A foreclosure attorney may receive instructions from the servicer, even though the underlying financial interest belongs to another entity.
Understanding these relationships can help explain why mortgage default cases sometimes involve several organizations with different responsibilities.
When State Laws Conflict With Standardized Procedures
A national foreclosure operation benefits from standardized workflows.
But foreclosure law remains heavily dependent on the location of the property.
Some states require extensive court involvement.
Others rely primarily on recorded notices and trustee sales.
Certain states provide statutory redemption rights under specified circumstances, while others impose different restrictions on the borrower's ability to recover property after a completed sale.
Rules governing deficiency judgments, notice delivery, foreclosure mediation, and lien enforcement also vary.
A procedure suitable for one jurisdiction may be legally insufficient in another.
National service providers must therefore maintain accurate state-specific requirements and update their practices when laws change.
The challenge is not merely knowing that different rules exist.
It is ensuring that the correct rules are applied to the correct property at the correct stage of the process.
That requires coordination among compliance personnel, legal professionals, mortgage servicers, and technology providers.
The Homeowner's Difficulty Identifying the Right Party
For homeowners, the structure of nationwide foreclosure operations can make an already difficult situation more confusing.
A borrower may receive monthly statements from one company, mortgage assistance communications from another department, and foreclosure notices identifying a separate law firm or trustee.
The mortgage owner may not be the company collecting payments.
The organization coordinating legal referrals may not be the attorney appearing in court.
A property valuation may be prepared by an outside vendor that has no direct relationship with the borrower.
These distinctions are ordinary features of modern mortgage servicing, but they can complicate attempts to resolve disputes.
A homeowner questioning an account balance may need to contact the servicer.
A challenge to a pending judicial foreclosure may require action in the court where the case is filed.
A dispute involving a trustee sale may require compliance with state-specific procedures and deadlines.
There is no universal method for resolving every foreclosure dispute.
The correct approach depends on the nature of the problem and the legal authority of the parties involved.
Nationwide Efficiency Versus Individual Accountability
The economic reasons for centralized foreclosure operations are understandable.
Financial institutions managing large mortgage portfolios need systems capable of tracking defaults, complying with deadlines, coordinating legal work, and maintaining records.
Without organized procedures, the administrative burden could be substantial.
Centralization can also support better oversight by allowing institutions to monitor cases and identify compliance issues across their portfolios.
But efficiency creates a corresponding obligation to preserve individualized accuracy.
A borrower is not merely an account number.
A property is not simply an asset entry in a servicing database.
Each foreclosure involves a specific debt, a particular parcel of real estate, and legal rights that must be respected.
A standardized process must therefore accommodate circumstances that cannot be resolved through routine administrative steps.
Those circumstances may include disputed payments, pending assistance applications, bankruptcy protections, questions concerning enforcement authority, and court orders.
The challenge for nationwide default-service networks is to achieve operational efficiency without allowing the scale of the system to diminish accountability.
The Future of Mortgage Default Legal Services
The foreclosure industry will likely continue to rely on centralized technology, specialized legal providers, and coordinated servicing networks.
Electronic document management, automated compliance checks, and increasingly sophisticated data systems can help organizations administer complex portfolios.
Emerging technologies may further change how documents are reviewed, valuations are generated, and foreclosure deadlines are monitored.
But greater automation also creates new questions about verification and supervision.
Who confirms that the information entering a system is accurate?
Who determines whether a foreclosure may lawfully proceed?
Who is responsible for recognizing circumstances that require a legal hold?
And who has authority to correct an error before a property is sold?
These questions cannot be answered by technology alone.
They require clear legal duties, reliable procedures, competent professional oversight, and effective mechanisms for identifying mistakes.
Behind Every Foreclosure Is a Chain of Responsibility
A foreclosure may begin with a missed mortgage payment, but the path from delinquency to property sale can involve numerous participants.
The mortgage servicer maintains the loan account.
The investor holds the financial interest.
The national coordinator may organize default-related work.
Local attorneys and trustees perform jurisdiction-specific functions.
Property valuation specialists assess collateral.
Technology providers support the systems connecting these activities.
Each participant may perform a legitimate and necessary function.
Yet the complexity of the system makes accountability especially important.
When a homeowner disputes a foreclosure, understanding the chain of responsibility can be essential to determining whether the correct procedures were followed.
The defining challenge for America's nationwide foreclosure industry is not simply whether it can process mortgage defaults efficiently. It is whether every foreclosure, regardless of how many organizations participate, remains subject to accurate records, lawful procedures, meaningful oversight, and accountability for the decisions that lead to the loss of a home.
For homeowners, lenders, investors, and legal professionals alike, the integrity of that process matters far more than the speed with which a case can be completed.