Mortgage assistance programs are intended to help struggling homeowners avoid foreclosure. But between complicated applications, servicing deadlines, and simultaneous collection efforts, the process of saving a home can become a race against time.
A homeowner falls behind on mortgage payments after losing a job. Rather than abandoning the property, the borrower contacts the mortgage company, explains the hardship, and requests a loan modification.
The company asks for financial statements, tax returns, bank records, and proof of income. The homeowner submits the documents and waits for a decision.
Meanwhile, collection notices continue arriving.
Then comes another letter: the property is scheduled for foreclosure.
For borrowers unfamiliar with the mortgage servicing industry, this situation can seem contradictory. How can a company be considering an application to save a home while simultaneously pursuing the legal process to take it?
The answer lies in a complicated system known as mortgage loss mitigation, where foreclosure prevention, loan servicing, investor requirements, and legal enforcement intersect.
Federal law establishes protections intended to prevent certain foreclosure activities while qualifying applications are under review. But those protections are conditional, and understanding when they apply can make the difference between preserving a home and losing it.
What Is Mortgage Loss Mitigation?
Loss mitigation is the process through which a mortgage servicer evaluates alternatives to foreclosure when a borrower is experiencing financial difficulty.
A mortgage servicer is generally the company responsible for administering the loan, collecting payments, maintaining account records, and communicating with the borrower.
The servicer may be different from the institution that owns the mortgage.
When a borrower defaults, the servicer may evaluate options intended to resolve the delinquency while reducing potential losses to the mortgage owner or investor.
These options can include:
Loan modifications. Changes to the original mortgage terms, potentially involving the interest rate, repayment period, or treatment of overdue amounts.
Repayment plans. Arrangements allowing borrowers to pay missed installments over an agreed period while resuming regular payments.
Forbearance. Temporary reductions or suspensions of required payments during a financial hardship. Forbearance generally postpones payments rather than forgiving the debt.
Short sales. Transactions in which a property is sold for less than the outstanding mortgage balance with the required approval of the mortgage holder or servicer.
Deeds in lieu of foreclosure. Agreements under which a homeowner voluntarily transfers ownership to the lender or another authorized party instead of proceeding through foreclosure.
Each option has different eligibility requirements and financial consequences.
Some allow the homeowner to remain in the property. Others provide an alternative method of transferring ownership.
The availability of assistance depends on factors including the loan's ownership, applicable investor rules, the borrower's circumstances, and the servicer's programs.
Why a Loan Modification Is Not Guaranteed
A homeowner may assume that demonstrating financial hardship should be enough to obtain a loan modification.
In reality, mortgage modifications are subject to eligibility criteria.
The servicer may examine household income, monthly expenses, existing mortgage terms, outstanding arrears, and the borrower's ability to maintain future payments.
The mortgage owner or investor may also impose restrictions on available modifications.
For example, an arrangement that temporarily lowers payments might not resolve the problem if the borrower cannot afford the modified amount over the long term.
Conversely, a borrower with sufficient income to resume payments may still encounter difficulties if the proposed modification does not adequately address accumulated arrears.
Federal mortgage-servicing rules generally require covered servicers to follow specified procedures when evaluating qualifying applications.
But the rules do not create a universal entitlement to a loan modification.
A servicer can deny an application when the borrower does not qualify under the applicable program requirements, provided the servicer complies with governing law.
This distinction is central to understanding the system: the right to a legally compliant review is not the same as a guaranteed right to mortgage assistance.
The Problem of Dual Tracking
One of the most controversial issues in mortgage servicing is known as dual tracking.
The term generally describes situations in which foreclosure activity proceeds while a borrower is simultaneously seeking assistance to avoid foreclosure.
Historically, concerns about dual tracking arose when homeowners reported submitting modification applications while foreclosure departments continued advancing their cases.
A borrower might be asked to provide additional financial documents even as an auction date approached.
Federal mortgage-servicing regulations now restrict certain forms of this practice.
Under Regulation X, 12 CFR § 1024.41, covered servicers must comply with procedural protections when borrowers submit qualifying loss mitigation applications.
The rules distinguish between foreclosure activity that has not yet begun and proceedings that are already underway.
For many covered loans, a servicer generally cannot initiate foreclosure until the borrower is more than 120 days delinquent, subject to specified exceptions.
If a complete loss mitigation application is received before foreclosure begins, the regulations may prohibit initiating foreclosure until the required evaluation process has been completed and the applicable conditions for proceeding are satisfied.
If foreclosure has already begun, receiving a complete application more than 37 days before a scheduled sale generally restricts the servicer from obtaining a foreclosure judgment or order of sale, or conducting the sale, until specified conditions are met.
The rules do not prohibit every administrative step associated with an existing foreclosure. Their restrictions apply to particular actions and stages of the process.
The timing and completeness of the application therefore matter enormously.
When Is a Mortgage Assistance Application Considered Complete?
One of the most consequential disputes in loss mitigation involves whether the homeowner has submitted a complete application.
A borrower may believe an application is complete after uploading financial documents or mailing a package to the mortgage company.
The servicer may determine that additional information is required.
Under federal regulations, a complete loss mitigation application generally means that the servicer has received all information it requires to evaluate the borrower for available assistance options.
Depending on the circumstances, requested information may include income verification, bank statements, tax documents, hardship explanations, and other supporting materials.
Servicers must exercise reasonable diligence in obtaining the information needed to complete an application.
For applications received at least 45 days before a scheduled foreclosure sale, the regulations generally require timely written acknowledgment identifying whether the application is complete or what additional information is needed.
Special rules also address applications that appear complete based on the servicer's stated requirements but are later found to need additional information.
These requirements are intended to prevent uncertainty about whether a borrower has reached the stage at which important protections apply.
Nevertheless, borrowers can encounter difficulties when documents become outdated, requests are unclear, or communications are inconsistent.
A dispute over one missing document can have serious consequences when a foreclosure deadline is approaching.
The 37-Day Rule and the 30-Day Review Period
Federal mortgage-servicing regulations establish important timing requirements for loss mitigation reviews.
When a covered servicer receives a complete loss mitigation application more than 37 days before a scheduled foreclosure sale, it generally must evaluate the borrower for available loss mitigation options and provide a written decision within 30 days, subject to regulatory provisions addressing particular circumstances.
The 37-day threshold is especially significant because it affects the protections available under the federal rule.
An application submitted too close to a scheduled sale may not trigger the same review and foreclosure restrictions, although other laws, investor requirements, or servicing obligations may still apply.
Borrowers who submit complete applications sufficiently early may also have rights concerning written explanations for certain modification denials and opportunities to appeal.
For example, under specified conditions, a borrower who submits a complete application at least 90 days before a foreclosure sale may have a right to appeal the denial of a trial or permanent loan modification.
These procedural requirements do not guarantee approval.
They do, however, establish standards for how covered servicers must handle qualifying applications.
For a homeowner, the difference between submitting an application 60 days before a sale and submitting it only a few days before the sale can be substantial.
When Mortgage Servicing Departments Fail to Communicate
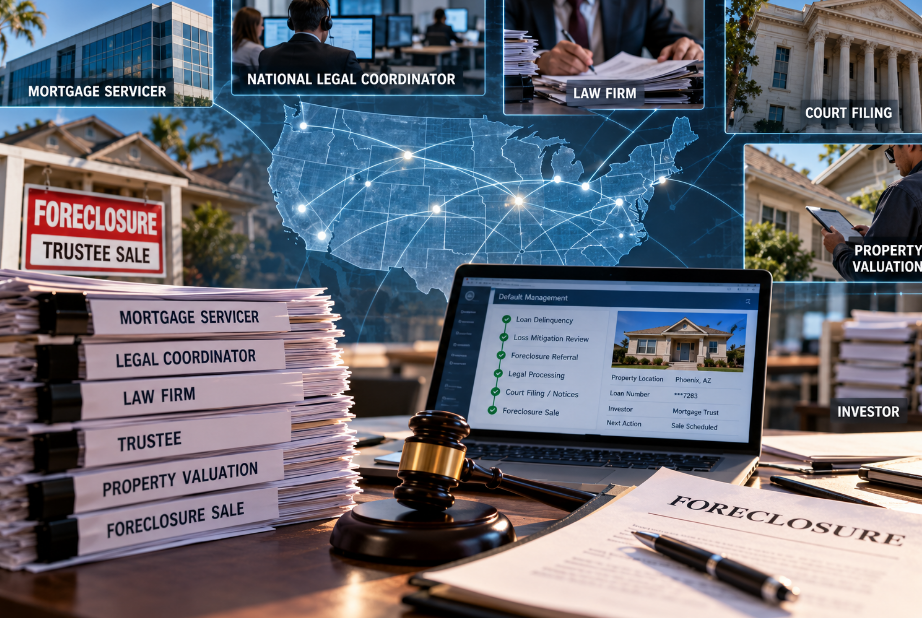
Mortgage servicing operations often involve separate personnel responsible for payment collection, borrower assistance, foreclosure referrals, document processing, and legal compliance.
A foreclosure law firm or trustee may also be involved.
This organizational structure creates a need for accurate and timely communication.
If a homeowner submits a complete application that triggers foreclosure protections, the appropriate departments and outside legal representatives must act consistently with those restrictions.
The official interpretation of Regulation X specifically addresses communications with foreclosure counsel.
Where the applicable prohibition prevents a foreclosure judgment or sale, the servicer must take appropriate steps to ensure that its attorneys do not proceed with prohibited actions.
A servicer cannot automatically escape responsibility by attributing a violation to outside foreclosure counsel.
That principle matters because the homeowner typically does not control how information moves between the servicing company and its contractors.
The borrower may communicate with one representative while legal proceedings are being managed elsewhere.
A reliable servicing system must account for both activities.
Why Homeowners Sometimes Receive Conflicting Information
Mortgage assistance reviews can involve multiple stages and changing financial information.
A borrower may initially qualify for one program but later become ineligible because income changes or required documentation is not supplied.
A temporary forbearance arrangement may expire before a permanent repayment solution has been established.
A trial modification may require several successful payments before permanent terms become effective.
Additionally, borrowers may speak with different representatives who have access to different parts of the servicing record.
These circumstances can produce confusion even when no legal violation has occurred.
However, inaccurate statements, improper document handling, or failures to observe required procedures may create separate legal concerns.
The distinction is important.
Not every denial or delay constitutes misconduct. But a servicer's compliance with its obligations must be evaluated independently of whether the borrower ultimately qualifies for assistance.
What Happens When a Modification Is Denied?
A denial does not always mean that foreclosure must immediately proceed.
The borrower may be eligible for another form of assistance, have an opportunity to appeal, or possess rights under state law or applicable investor programs.
Federal regulations require written explanations for certain loan modification denials, including relevant information about the reasons for the decision.
Where appeal rights apply, the borrower must receive the opportunity prescribed by the regulation.
An appeal generally concerns the servicer's evaluation of the modification application, not a universal right to renegotiate the mortgage.
Borrowers may also seek assistance from housing counselors or attorneys to understand the decision and available alternatives.
The Consumer Financial Protection Bureau directs struggling homeowners toward HUD-approved housing counseling services, which may be available without charge.
The agency also warns consumers about foreclosure rescue scams that promise guaranteed modifications or demand improper upfront payments.
When Foreclosure Prevention Becomes a Race Against Time
The effectiveness of loss mitigation often depends on when the homeowner seeks assistance.
A borrower who contacts the servicer shortly after experiencing financial difficulty may have more time to gather documents, correct incomplete submissions, and consider alternatives.
A borrower who waits until an auction has been scheduled may face much narrower options.
This does not mean late applications are necessarily futile.
Different mortgage programs, state laws, and individual circumstances may provide additional protections or alternatives.
But a pending request for assistance should never be assumed to automatically cancel or postpone a scheduled foreclosure sale.
The homeowner must understand whether a specific legal restriction, approved arrangement, court order, or confirmed postponement actually prevents the sale from proceeding.
This distinction can be particularly important when communications with the servicer are informal or ambiguous.
The Business Interests Behind Loss Mitigation
Loss mitigation is often presented primarily as a homeowner assistance function.
It is also an important financial and operational component of the mortgage servicing industry.
Foreclosure can be expensive.
The process may involve legal fees, property inspections, valuation services, maintenance expenses, taxes, insurance, and the eventual disposition of real estate.
A successful loan modification may allow the mortgage owner to recover more value than a foreclosure.
But not every modification produces that result, and investors may evaluate potential outcomes differently depending on the loan and property.
Mortgage servicers must operate within contractual arrangements, investor requirements, regulatory obligations, and applicable state law.
These overlapping interests help explain why loss mitigation is a specialized business function rather than a simple customer-service accommodation.
They also raise an important question about accountability.
When a servicer evaluates a borrower for assistance, the process must satisfy the applicable legal requirements regardless of the financial interests of the parties involved.
The Difference Between Offering Assistance and Providing Meaningful Review
A mortgage company may advertise assistance programs, provide application forms, and maintain a department devoted to helping delinquent borrowers.
Those features alone do not establish that every application is handled correctly.
Meaningful loss mitigation requires timely communication, accurate records, appropriate evaluation, and compliance with restrictions governing foreclosure activity.
For homeowners, the stakes are substantial.
An incomplete application, missed deadline, inaccurate account record, or failure to communicate with foreclosure counsel can affect whether a borrower has a realistic opportunity to preserve a home.
For servicers, the challenge is administering large numbers of loans while ensuring that individual cases receive the attention required by law.
The fundamental question is not simply whether mortgage assistance programs exist. It is whether the procedures governing those programs provide homeowners with a genuine opportunity to obtain review before foreclosure becomes irreversible.
When a homeowner is trying to save a property, the outcome should depend on the applicable law, the loan's terms, the available assistance programs, and the borrower's circumstances—not on avoidable breakdowns in communication or document handling.
That is the central accountability challenge facing America's mortgage loss mitigation system.