In many states, a lender can initiate the sale of a homeowner's property without first obtaining a foreclosure judgment. The process is legal, but it places enormous importance on notices, deadlines, trustees, and the homeowner's ability to challenge a sale before it happens.
For a homeowner facing foreclosure, one of the most unsettling discoveries may be that no judge is necessarily required to approve the loss of the property.
There may be no lawsuit, no courtroom hearing, and no opportunity to present a defense before a judge unless the homeowner takes affirmative legal action.
Instead, a foreclosure can proceed through a series of notices, recorded documents, statutory waiting periods, and a public auction conducted by a trustee or another authorized party.
This process is known as nonjudicial foreclosure, and it is a significant component of the American mortgage default industry.
Although it is governed by state law and subject to legal restrictions, nonjudicial foreclosure raises fundamental questions about property rights, procedural protections, and the balance between a creditor's ability to enforce a mortgage and a homeowner's opportunity to contest the loss of a home.
How Foreclosure Can Happen Without a Lawsuit
When a homeowner obtains a mortgage loan, the transaction generally includes a promissory note establishing the debt and a mortgage or deed of trust securing repayment with the property.
In many states, a deed of trust contains a power-of-sale provision. This provision authorizes foreclosure through a prescribed procedure when the borrower defaults, without requiring the creditor to first obtain an ordinary judicial foreclosure judgment.
The power to conduct the sale does not mean that a lender can simply seize a property whenever a payment is missed.
State laws establish requirements governing default notices, opportunities to cure, public notice, sale procedures, and the authority of the party conducting the foreclosure.
Federal mortgage-servicing rules may impose additional restrictions.
The fundamental difference is that these protections do not necessarily involve a judge reviewing the foreclosure before the property is sold.
In a judicial foreclosure, the lender generally files a lawsuit and must obtain the appropriate court judgment or order before the sale proceeds.
In a nonjudicial foreclosure, the process can advance administratively unless a legal requirement prevents it or someone successfully intervenes.
For homeowners, that distinction can be decisive.
The Trustee's Role in Taking a Home to Auction
Nonjudicial foreclosure often involves a trustee named in a deed of trust or a substitute trustee appointed under applicable law.
The trustee's function is different from that of the mortgage lender.
The lender or other authorized beneficiary holds the secured financial interest, while the trustee carries out specified duties associated with the deed of trust and foreclosure process.
Depending on state law, those duties may include recording notices, providing required information, conducting the public auction, accepting bids, and transferring title to the successful purchaser.
Trustees may be individuals, attorneys, specialized foreclosure-service companies, or other entities authorized to perform the role.
Some operate on a large scale, administering foreclosure transactions for mortgage servicers and financial institutions.
This arrangement creates an important question: What obligations does the trustee owe to the homeowner whose property is being sold?
The answer varies by jurisdiction.
Trustees are not necessarily neutral adjudicators in the way judges are. Their duties arise from the governing instruments and applicable law, and the scope of those duties differs among states.
A trustee's involvement therefore should not be confused with independent judicial review of whether every aspect of the underlying debt and foreclosure is legally correct.
From Missed Payments to a Foreclosure Sale
A nonjudicial foreclosure generally develops through several stages.
The homeowner first becomes delinquent on the mortgage. The servicer may send collection notices, explain available assistance programs, and attempt to resolve the default.
For many residential mortgage loans covered by federal servicing rules, the servicer generally cannot make the first notice or filing required to initiate foreclosure until the loan is more than 120 days delinquent, subject to specific exceptions.
Once foreclosure is legally permitted to begin, the authorized party must comply with the applicable state's notice and procedural requirements.
In California, for example, the process commonly involves recording a notice of default, allowing a statutory period to pass, and subsequently recording and providing notice of a trustee's sale.
Texas follows a different framework. For many residential deed-of-trust foreclosures, state law requires notice of the sale at least 21 days before the auction, along with applicable notice-of-default and cure requirements.
These differences demonstrate why there is no single nationwide foreclosure timetable.
A borrower in one state may face substantially different procedural deadlines from a borrower in another.
The process ultimately may lead to a public auction, where eligible bidders compete to purchase the property.
If no third-party bidder offers enough to purchase it, the secured creditor may acquire the property through a credit bid, subject to applicable law.
The transfer of ownership can then create additional consequences involving possession, eviction procedures, junior liens, and potential remaining debt obligations.
What Happens When the Foreclosure Documents Are Wrong?
Because nonjudicial foreclosure does not necessarily require a court to examine the case in advance, the accuracy of documents and compliance with statutory procedures become especially important.
Potential disputes can involve an incorrect loan balance, payments that were not properly credited, defective notices, problems with the authority of the foreclosing party, or failures to comply with required waiting periods.
Not every error invalidates a foreclosure. Courts distinguish among different types of defects, and the consequences depend on state law, the nature of the error, and whether the homeowner can establish the required elements for relief.
Nevertheless, the possibility of mistakes raises a serious procedural concern.
In a judicial foreclosure, contested issues can be presented within the foreclosure lawsuit.
In a nonjudicial foreclosure, the homeowner may need to initiate a separate legal action to obtain review.
That can require identifying the correct defendants, understanding the applicable law, assembling supporting evidence, and requesting judicial intervention before a scheduled sale.
For borrowers already experiencing financial hardship, those steps can be difficult.
Can a Homeowner Stop a Nonjudicial Foreclosure?
A nonjudicial foreclosure is not necessarily irreversible simply because the lender has started the process.
Depending on the circumstances, a homeowner may be able to cure the default, reinstate the loan, negotiate a repayment arrangement, obtain a loan modification, refinance, sell the property, or pursue other available alternatives.
A homeowner may also have grounds to challenge a foreclosure in court.
Such challenges can involve violations of state foreclosure statutes, federal mortgage-servicing protections, contractual requirements, or other applicable legal duties.
Where legally justified, a homeowner may seek a temporary restraining order or preliminary injunction to prevent a sale while a dispute is considered.
But filing a lawsuit does not automatically stop a foreclosure. Judicial relief ordinarily requires satisfying specific legal standards, and timing is critical.
Some defenses or remedies may become more difficult after a completed sale, particularly where a third party has purchased the property and state law protects the purchaser's title.
That makes early identification of potential errors particularly important.
Federal Protections Against Premature Foreclosure
Although foreclosure procedures are largely established by state law, federal regulations provide significant protections for many residential mortgage borrowers.
Under the Consumer Financial Protection Bureau's Regulation X, covered mortgage servicers generally must observe the 120-day delinquency restriction before initiating foreclosure, with specified exceptions.
The regulations also address situations in which a homeowner submits a complete application for loss mitigation.
If the servicer receives a complete application more than 37 days before a scheduled foreclosure sale, it generally must evaluate the borrower for available loss mitigation options within 30 days.
Certain restrictions also prevent a servicer from conducting a foreclosure sale while the borrower remains entitled to the applicable loss mitigation protections.
These rules are designed in part to address situations in which homeowners seek mortgage assistance while foreclosure activity continues.
However, federal regulations do not guarantee that every borrower will receive a loan modification, and not every loan or servicer is subject to identical requirements.
The protections depend on the facts, timing, and applicable regulations.
Why the Foreclosure Industry Uses Nonjudicial Procedures
From the perspective of lenders and mortgage investors, nonjudicial foreclosure offers practical advantages.
Judicial proceedings can involve substantial legal expenses, contested hearings, court scheduling, and extended timelines.
A properly conducted nonjudicial foreclosure may allow the creditor to recover collateral more quickly and at lower administrative cost.
That efficiency can be particularly important for institutions managing large portfolios of delinquent loans.
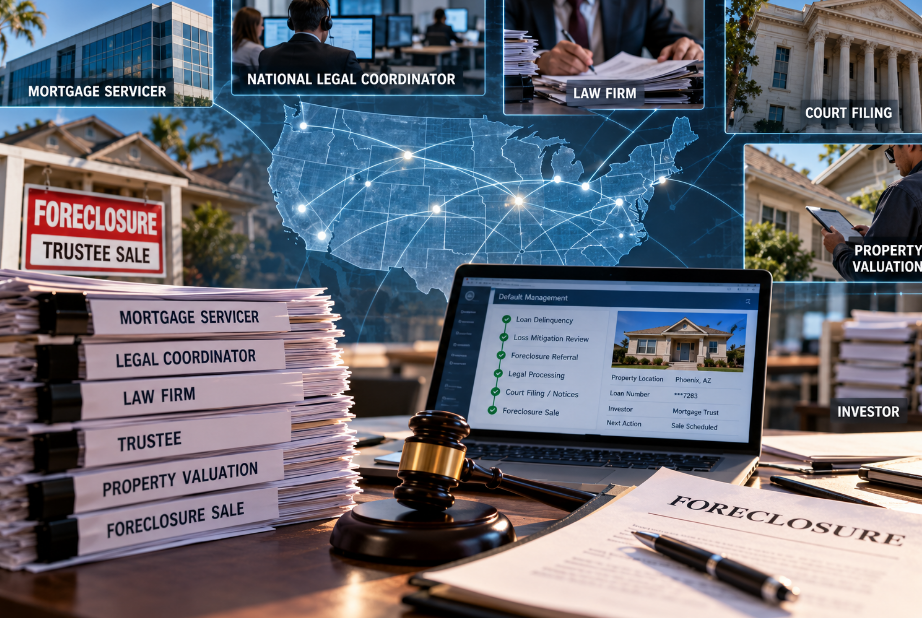
Mortgage servicers, trustees, and default-service providers may use standardized procedures and case-management technology to track notices, deadlines, documentation, and scheduled auctions.
Such systems can help maintain consistency across large numbers of cases.
But standardization also creates a need for reliable controls.
A system capable of processing thousands of foreclosures must still recognize circumstances requiring individualized attention, including disputed balances, pending loss mitigation applications, bankruptcy proceedings, and court orders.
The efficiency of a foreclosure operation cannot substitute for compliance with the laws governing each individual property.
The Question of Due Process
Nonjudicial foreclosure also raises broader questions about procedural fairness.
The Fifth and Fourteenth Amendments restrict certain government deprivations of property without due process of law. However, those constitutional protections generally require qualifying governmental action; a privately conducted foreclosure does not automatically constitute state action merely because state law authorizes it.
Courts have considered constitutional challenges to nonjudicial foreclosure systems, including questions about the extent of government involvement.
Separately from constitutional requirements, state legislatures establish statutory procedures intended to protect borrowers and regulate the exercise of foreclosure rights.
The policy debate therefore extends beyond whether nonjudicial foreclosure is legally permissible.
It concerns whether the available notices, opportunities to cure, and avenues for judicial review provide meaningful protection before a homeowner loses title to a property.
Supporters of nonjudicial foreclosure emphasize the importance of enforcing valid security interests without unnecessary litigation.
Critics question whether borrowers facing complex financial and legal disputes have a realistic opportunity to prevent an improper sale.
Both concerns help explain why foreclosure law continues to balance creditor remedies against borrower protections.
A Property Sale With Enormous Consequences
Nonjudicial foreclosure may be conducted without a courtroom, but its consequences are no less significant than those of a judicial foreclosure.
A completed sale can result in the loss of a family home, accumulated equity, and the legal right to possess the property.
It may also affect a borrower's credit, financial stability, and future housing opportunities.
For mortgage investors and servicers, foreclosure represents the enforcement of a contractual security interest.
For homeowners, it can represent the loss of one of their most valuable assets.
The central issue is not whether lenders should possess lawful remedies when borrowers default. Such remedies are an established part of mortgage lending.
The issue is whether those remedies are exercised accurately, lawfully, and with adequate opportunity for homeowners to protect their rights.
When a home can be sold without a judge first reviewing the foreclosure, the integrity of the notices, the conduct of the trustee, the actions of the mortgage servicer, and the availability of timely legal remedies become the safeguards upon which the entire process depends.
Understanding those safeguards is essential for anyone confronting the possibility of losing a home outside the courtroom.